Bankability: Why a Profitable Project May Still Be Unfinanceable
Finding a good real estate project has never been easy. A developer needs the right site, the right permits, realistic construction costs and enough market demand, plus a margin that makes the risk worthwhile. In the years ahead, another question may become just as decisive: can the project actually be financed?
Europe needs enormous investment in housing, building renovation, infrastructure and the energy transition. The European Commission estimates the continent will need roughly €750–800 billion of additional investment every year until 2030 to meet its economic and strategic objectives.[1] So the issue isn’t whether capital exists. It does. The issue is whether the right projects can attract it. That’s the concept behind bankability.
A profitable project is not necessarily a bankable one
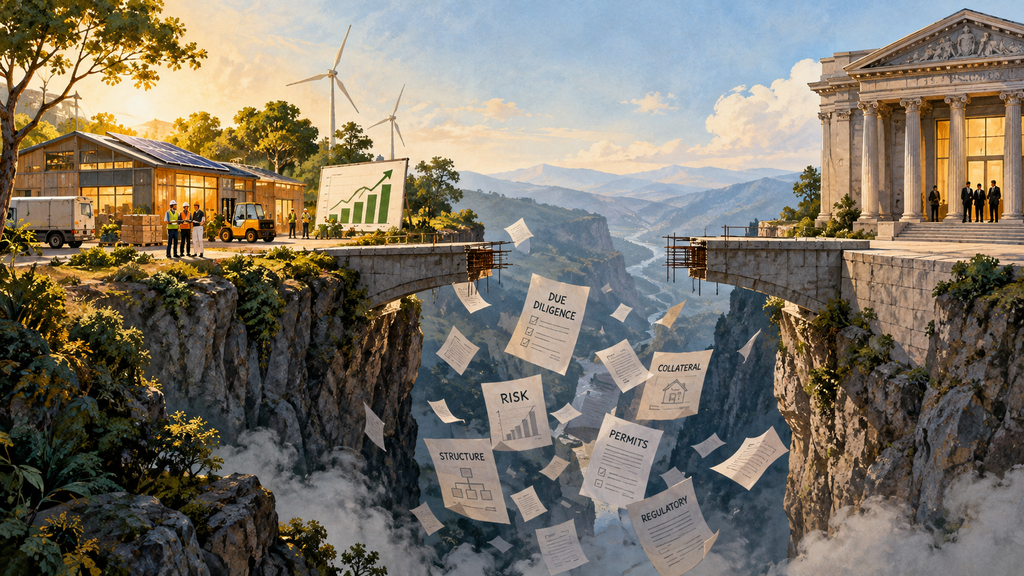
Profitability and bankability may seem like two ways of describing one and the same thing, but they are in fact two separate issues. Profitability is a measure of whether the project makes economic sense: Bankability asks whether it’s structured in a way that a lender is comfortable financing.
A development can have a strong location, clear demand and an attractive margin, and still struggle to secure the full financing it needs. A lender considers many other factors besides the headline return: how much equity the developer is investing, what security can be taken, pre-sales achieved, source of debt repayment, track record of the developer, construction program, legal structure, feasibility of the project if costs rise or sales slow. A project can look excellent on a spreadsheet and still raise hard questions from a financing perspective. That doesn’t make it a bad Project. It means economic viability and financial viability aren’t the same thing.
Banks have their own constraints
Banks don’t lend purely on whether they like a project. They operate within a regulatory framework that dictates how different types of risk must be treated. The European CRR III Regulation, for instance, distinguishes between several categories of real estate exposure and applies specific treatment to transactions involving land acquisition, development and construction.[2]
That means a bank can believe in the commercial logic of a development and still decline to finance the full amount requested, not because of the project’s quality, but because a particular layer of risk doesn’t fit its lending criteria, capital requirements or internal limits. “We won’t finance this part of the project” does not mean “this is a bad project.” It may simply mean that this particular risk sits outside the lender’s comfort zone. Understanding that distinction can completely change the direction of a financing negotiation.
Good projects compete for capital too
We usually think of capital chasing opportunities: investors search for good assets, banks search for strong borrowers, funds look for attractive transactions. The relationship also runs the other way. Good projects compete for good capital.
Two developments with nearly identical expected returns can receive very different financing offers, because capital providers aren’t looking only at potential profit. They’re weighing the quality of the information, the developer’s experience, the equity at risk, the transparency of the structure, the credibility of the assumptions, and perhaps above all, how clearly they understand the path to getting their money back. A developer who presents those elements well doesn’t just improve their odds of securing financing; they often improve the terms available to them: a more appropriate capital structure, more flexibility, access to a wider pool of lenders and investors. That’s why bankability is starting to function less like a purely financial concept and more like a competitive advantage.
The question is changing
For years, the first question behind most development opportunities has been whether the project is profitable, and that question remains essential . A strong financing structure can support a good project, but it cannot fix a project that does not work on its own. But profitability is increasingly only the first part of the analysis. The next question is whether the project is bankable: can it attract enough capital, on acceptable terms, to move from an Excel model to construction?
There’s a real difference between identifying a profitable opportunity and being able to execute it, and in the next European real estate cycle that difference is likely to matter more, not less. The developers with the strongest opportunities won’t necessarily be the ones who find the best sites first. They’ll be the ones who know how to make those opportunities financeable.
Bibliography
[1] European Commission. “Savings and Investments Union Strategy to Enhance Financial Opportunities for EU Citizens and Businesses”, 2025.
[2] European Parliament and Council of the European Union. Regulation (EU) 2024/1623, CRR III.
This article is for informational purposes only and does not constitute financial, legal or tax advice.